
Curling Betting in Great Britain for 2026: How the Markets Work and What the Odds Cost
 Available in US
Last checked: 27 October 2026 against the Gambling Commission’s public register and the operators’ own terms.
Curling is small. The audience is small, the calendar is small, the menu of available markets is small, and the prices get thinner the further down the fixture list a reader goes. None of that is an argument for treating it casually. The opposite — that curling is a niche market — is the reason a writer on this subject earns their keep: most readers land on the page having been led to it by a single Olympic window or a single weekend of the World Curling Tour, with no idea how an end is settled, why one price is sitting at 1.90 and another at 2.10, or why a bookmaker with a famous Premier League sponsor and a bookmaker with an Essex racing licence are both equally legal to bet with under a single line of statute. The pages below are written for that reader.
The angle is consequence. Almost everything in this sport’s betting life is settled by what flows from a few small decisions — the licence one books under, the team structure of the operator, the structure of the markets themselves. Whether a price of 1.90 is generous, whether a free bet is worth clearing, whether a regulatory change in the next twelve months means anything to someone who only bets on curling — the answers all hang off the same handful of facts. The book is organised around them.
What Curling Betting Actually Is
Curling betting is not a separate product. It is a thin column inside a bookmaker’s sportsbook — usually accessed under winter sports, sometimes filed under “other” or folded into a seasonal tab that appears for the weeks around an Olympic Games, a World Championship or a Grand Slam of Curling leg. The thinness is structural. Bookmakers will only staff an in-house trading team for a sport when the handle justifies it; for most of the year, curling is either entirely absent from the book or carried on a third-party feed that re-publishes prices from one or two specialist suppliers. That has consequences for what a punter sees and what the punter pays.
First, the menu shrinks. A premier-market sport such as football carries hundreds of pre-match markets on a single Premier League game — the match result, the handicap, total goals, both teams to score, corners, cards, player shots, player fouls, a builder that combines any of the above. Curling has the match result and a couple of derived markets in front of it. It does not have a betting exchange on it, outside the few markets bettors themselves build on an exchange. There is no each-way equivalent for most curling events. The proposition that drives sports betting in this country — the multi-leg acca — almost always has to skip curling because the price of every leg multiplies, and one missing or restricted leg ruins the slip.
Second, the price gets eaten. A small sport running on a third-party feed is, mechanically, an uncompetitive market: one price, often from a single supplier, offered at the bookmaker’s margin rather than at the margin of a bookmaker trading the line in-house. The margin figures discussed later in this guide are not a quirk of curling in particular — they are what any two-way market looks like at even-money when the only alternative to a 1.90 quote is no quote at all.
Third, the calendar is what it is. The page is written for 2026, but the actual year-round cadence of the sport is fixed: the men’s and women’s World Curling Championships in the spring, the Continental Cup and the Champions Cup at points through the autumn, the Olympic cycle every four years, mixed doubles where it appears on the circuit, and the rest of the year filled by domestic play and tour stops that are sparsely covered outside North America. A reader who only finds curling markets at Olympic time should know that the same bookmaker has them all year, just on a smaller menu.
What this means for a punter: curling is not a sport to bet on speculatively. It is a sport to bet on when a specific match has a market, the price is one the punter has been able to think about, and the bookmaker is one this guide has already costed.
The Fundamentals of the Game a Bettor Needs to Know
The page is a betting guide rather than a coaching manual, but the betting prices rest on outcomes that are settled by the rules, not by an opinion column. Three pieces of knowledge do most of the work for a reader trying to read a price.
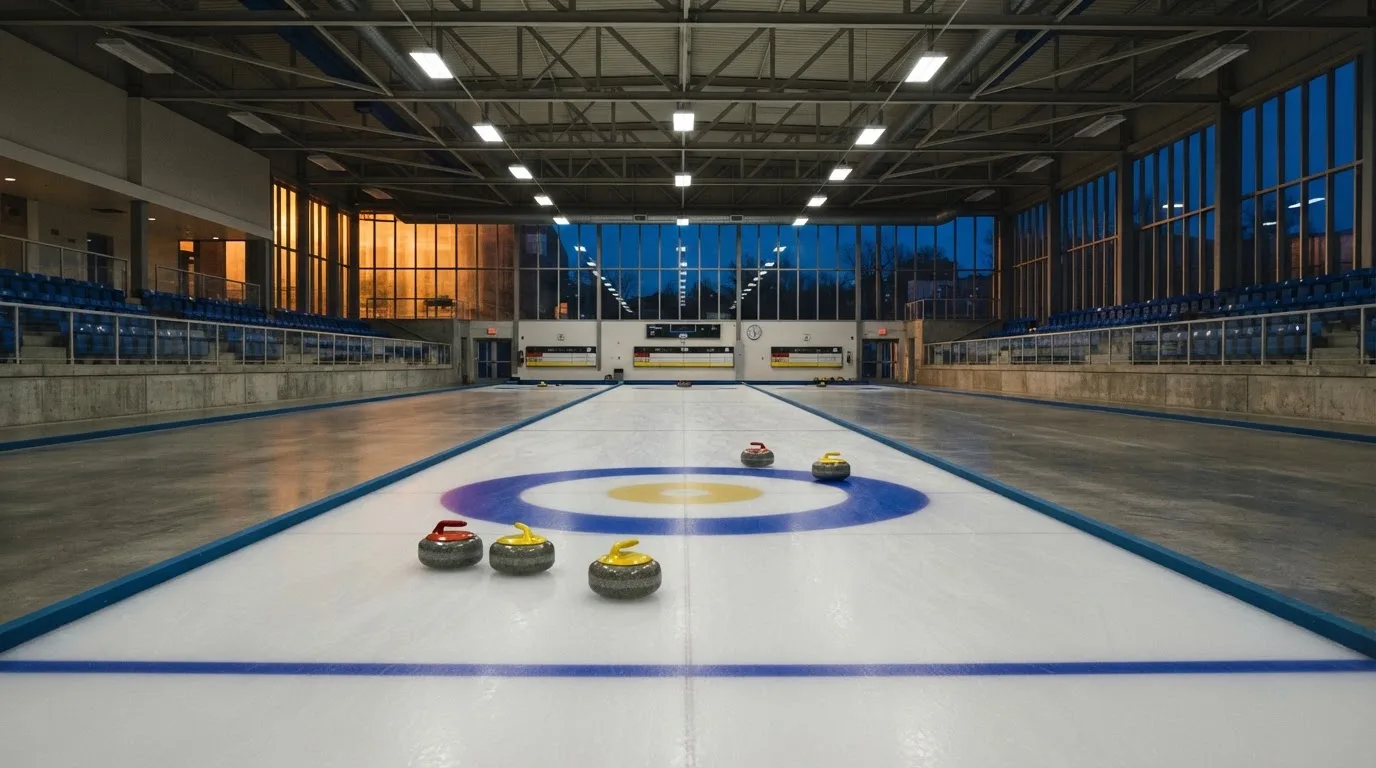
A curling team has 4 players (2 in doubles), and each player throws two of the team’s eight stones. Sixteen stones are thrown in an end: eight by one team, eight by the other, alternating. Curling games usually last 8 or 10 ends; international competitive games are generally 10 ends. The number of ends in a fixture changes its shape — a 10-end game carries more time for the trailing side to come back than an 8-end tie — but bookmakers settle prices on the result either way.
After all 16 stones of an end are thrown, the team with the stone closest to the button scores one point for each of its stones closer than the opponent’s nearest stone; only stones in the house count. That has two practical consequences. The first is the empty end — an end in which every stone is swept out of the house and no score is recorded; the team without the hammer in that end gets the hammer for the next one. The second is the big end: an end in which one team rings up four or five points with two stones in the house and no reply. A score of four or five changes the price of every running market on the game from that point.
Two small rule details surface in the markets. Tied curling games go to extra ends: a bookmaker offering a moneyline three-way (win, lose, draw) cannot carry a draw line because the game does not allow one — a tied game after ten ends is decided in an extra end rather than declared a draw. The hammer (last stone of an end) goes to the team that did not score in the previous end; if an end is blanked, the hammer stays with the same team. The hammer is the most consequential single fact in the betting frame: a team with the hammer in the last end is the favourite, every season, at every level of the sport. The way to read a curling price is to read it through the hammer.
To this, a reader should add the equipment. Curling stones weigh between 17.24 and 19.96 kg (38 to 44 lb) under World Curling Federation rules. The numbers matter only because betting markets sometimes include a total of ends — whether the game goes over or under a published number of ends, typically 9.5 — and the schedule of an extra end is settled by the rules rather than the referee.
The pieces fit together like this: a curling game runs an average of 10 ends of 16 stones, scored by the team with the closer stone(s) in the house, with the hammer cycling to the team that did not score, and tied games resolved by extra ends. Every market the bookmaker offers is a derivative of these facts.
The Legal Frame in Great Britain
Curling betting exists in Great Britain inside the same legal envelope as every other form of online betting: the Gambling Act 2005, the Gambling (Licensing and Advertising) Act 2014 in amendment, the Licence Conditions and Codes of Practice (LCCP) made under the Act, and the Commission itself. The relevant details for a punter are four.
The Gambling Commission is the regulator for Great Britain. Since the Gambling (Licensing and Advertising) Act 2014 any operator whose remote facilities are used in Great Britain needs a Commission licence wherever that operator is based — sections 33 and 36 of the 2005 Act as amended. A Curaçao, Maltese or Gibraltar licence is not a substitute. There is no state monopoly, no state list of permitted sports and no statutory cap on the number of licences. The Commission’s public register can be searched by business name, trading name, domain or account number and is the whole test of who holds a licence.
The licence categories the page deals with are remote general betting standard (real events) — which covers the betting side of a sportbook, including curling — and the various pool betting and exchange categories where the products differ. Curling itself is not a separately licensed “event class”; it is offered under whatever category the operator holds for real events. A bookmaker with a remote general betting standard (real events) licence can offer curling if it wants to and if it can find a feed to carry the prices.
The fourth and most consequential fact is the one a punter feels. Identity verification — name, address and date of birth — is mandatory before a customer can deposit or gamble, including with a free bet or bonus. This check has been in force since 7 May 2019 and it is the operational reason there is no anonymous play at a licensed site. It is also the rule that makes a comparison between a licensed bookmaker and an unlicensed one land where it does: the licensed operator is the one verifying the punter, and the unlicensed one isn’t.
That frame answers a question this page would otherwise have to keep answering. When this guide describes what a bookmaker offers — what it lists, what it promises, what its customer service does — it is describing what an operator does inside that licence. The licensing frame is the reason the rest of the page treats every review the same way.
What the Regulation Actually Does for a Punter
The frame is dense and the language is dense and the natural mistake is to read the dense bits as protection in the absence of a clear account of what protection actually flows from each rule. Below, the rules are taken one at a time, named for what they do and what they cost.
Identity verification is the price of doing business at a licensed site. The customer pays no fee; the customer pays the cost of a few minutes with a phone, an ID document and a proof of address, plus whatever time the operator takes to run the checks. In return the operator cannot let a minor open an account, cannot let a self-excluded customer reopen one, and cannot run gambling operations against the unknown. The downside is the one a regulated market accepts: the few customers who are prepared to lie about their identity, address and date of birth can still be detected at higher spend, with source-of-funds requests that go with the money-laundering rules, and any account that has been opened with false documents can be suspended. That is the trade: friction at the front, recourse at the back.
GAMSTOP is the national multi-operator online self-exclusion scheme, and a mandatory licence condition for online operators since 31 March 2020. Self-exclusion periods are six months, one year, five years, or five years with auto-renewal. After the minimum period the exclusion stays in place for a further seven years unless the customer asks GAMSTOP to remove it. GAMSTOP covers online sites and apps. Betting shops use a separate service. This is the single practical lever a punter can pull across every operator at once, including the ten in the comparison below.
The financial vulnerability check (LCCP condition 3.4.4, in force since 30 August 2024) applies to licensed remote betting when a customer’s deposits minus withdrawals exceed £150 in a rolling 30 days (since 28 February 2025). It is a public-record check — looking at indicators such as bankruptcy or county court judgments — not an income check and not a credit reference check. The check is a light one; the heavier financial risk assessments (the “affordability checks” referenced in the press) are part of a staged plan announced on 7 July 2026 and have no published start date yet. For a punter who only bets small amounts, none of this changes the front-end experience at all; for a punter who deposits heavily, this is the gating rule to know about.
Deposit limits (RTS 12) require operators to offer a gross deposit limit on a fixed time frame. The first changes have applied since 31 October 2025, a second phase was postponed to 30 September 2026, and whether it is live at the time of writing is not established. There is no state-set deposit or loss ceiling for betting: limits are the customer’s choice. A punter who wants to cap their own spend can do so on every operator’s account; a punter who hits the operator-side flag (the £150 figure, or whatever the live phase requires) is in territory where the rules differ by operator.
Financial spread betting is regulated by the Financial Conduct Authority, not the Commission. That matters only to the extent a bookmaker offers spread products on curling outcomes — most UK-facing bookmakers do not, and most sportsbooks that do offer them under a related FCA-authorised entity, not under the Gambling Commission. The punter should know the difference because the loss can exceed the deposit on a spread bet in a way it cannot on a fixed-odds bet.
There is no statutory cap on stakes in sports betting; operators set their own maximum stakes and may restrict customers. That is the rule that produces the punter’s most common frustration with curling: a request to a bookmaker to take a substantial amount on a curling line that, if it wins, returns more than the operator would like to pay.
The advertising rules are not licensed by the Commission. They run through the CAP Code (non-broadcast) and BCAP Code (broadcast), enforced by the ASA, alongside the LCCP marketing conditions. CAP Code section 16 holds that marketing must be socially responsible, must not be of strong appeal to under-18s, and no one who is or seems to be under 25 may be featured gambling or play a significant role in marketing. The promotional rules in force since 19 January 2026 cap wagering requirements on bonuses at 10x (a £10 bonus at 50x would require £500 of bets; the cap puts the figure at £100) and ban mixed-product promotions — any offer that requires gambling on two or more product types, for example “bet on football to get free spins” — outright.
Whether the bonus cap applies to free bets with no wagering condition, and any cap on the money value of a bonus, are not established in the public version of the rules. There is also no statutory rule on a maximum bonus amount, and no published rule on the maximum stake that may be used to clear a bonus. The “best odds guaranteed” pattern on horse racing — where a bookmaker pays the starting price if it is bigger than the price at which the bet was struck — is an operator’s own term, not a legal one.
Tax is a separate topic. The player pays no tax on betting winnings in Great Britain (general information, not tax advice; a professional gambler should ask HMRC or an adviser). General Betting Duty is the operator’s tax on gross profits, currently 15%. From 1 April 2027 a new remote betting rate of 25% applies within it, while remote bets on UK horse racing, bets on self-service betting terminals in licensed premises, pool betting and in-person betting stay at 15%. The remote rate stays at 15% until that date; whether operators pass duty on through odds is not established, and this page never states that the player is charged duty.
A British named-account rule, a state list of permitted payment methods and any rule for or against cryptocurrency deposits at licensed operators are not established: describe payments qualitatively and only from each operator’s terms, which is what this page does.
What Lives Behind an Unlicensed Site
An unlicensed site — one without a Commission licence, reached through search, through a social-media link, through an email, or through a friend — sits outside every rule described above. The protection the licensed frame provides does not apply. The customer has no Commission complaints route, no approved dispute-resolution body, no British consumer redress if funds are withheld, is not bound by the 10x bonus cap or the £150 vulnerability check, and is not in scope for GAMSTOP. The credit-card ban does not apply. The advertising rules do not apply. The wagering cap does not apply. The page does not editorially conclude that an unlicensed site is unsafe — that is a competitive judgement a punter makes for themselves. It does conclude that none of the British protections follow an account that lives outside the British licence.
Providing gambling facilities in Great Britain without the licence the Act requires is an offence under section 33 of the Gambling Act 2005 (on summary conviction up to 51 weeks’ imprisonment, a fine up to level 5, or both; six months in Scotland). It is aimed at the operator, not the customer. No offence aimed at a customer who merely bets on an unlicensed site was found in the rules reviewed for this page. Enforcement is disruption rather than blocking: cease-and-desist notices, search-engine referrals, work with registrars, hosts and payment providers, plus court-order DNS blocking powers that the Commission has been given, or is about to receive — ISP-level blocking is not in operation as a routine. The honest framing for the reader is the one this page uses: licensed = checks, limits, GAMSTOP, bonus cap, and verification before the first bet; unlicensed = none of those protections and possible loss of funds. Neither is “the safe choice” by default.
A reader who is comparing the licensed and unlicensed options is asked to weigh that trade. The arithmetic here is not personal: it is structural. If the operator is not subject to a dispute-resolution body and the operator’s own evidence can be challenged to no end, the punter has no safety net beyond the operator’s own commercial conscience. The ten reviewed brands are licensed; that is the precondition for appearing on this page.
Building the Match Calendar for 2026
The curling calendar for 2026 runs along the lines the World Curling Federation lays out at the end of the previous season. The major events on the schedule are: the World Men’s and World Women’s Curling Championships, run in late March or April; the Continental Cup, an international mixed team event that usually lives in late autumn or early winter; the Champions Cup and other points on the World Curling Tour, including the Grand Slam of Curling legs in North America; the European Curling Championships in late November or early December; the World Mixed Doubles Championship; and a number of smaller tour stops and qualification events. The Olympic cycle changes the calendar dramatically every four years: the page is written for 2026, an Olympic year if the cycle is on it, a non-Olympic year otherwise — and the difference is that the overall schedule through the Olympic year is structured around the qualification events at the end of the previous calendar year, with a noticeably heavier betting menu for several months either side of the Games. A reader using this guide outside the Olympic calendar will find the curling menu at most bookmakers reduces substantially between March and October.
Three further tournaments deserve a name. The Tour Challenge (formerly the World Curling Tour’s opening event) is the first big men’s and women’s tour stop of the season. The Canadian and US Olympic Trials carry major betting interest in North America and have started to appear on UK books. The mixed doubles discipline, first held at the Olympics in 2018, runs a separate parallel circuit with its own World Championship.
Curling became an official Olympic medal sport at the 1998 Winter Olympics; mixed doubles was first held at the Olympics in 2018. The relevant period for 2026 is the period in which the Olympic qualifying event for the next Winter Games (if 2026 precedes a Games year) is still running. A reader who is asking which events to look at now should look at the list above in roughly the order in which the season plays out.
What the Curling Markets Look Like in Practice
Curling carries a small but reliable menu of markets. Most bookmakers carry: the match result (two-way); an outright winner of the tournament, which is a futures market; a total-ends-over/under market, where the line is typically 9.5; and sometimes a market on a handicap, expressed as a half-end to make the line whole. A few books carry a half-time (mid-game) market on a curling game, a “first end” market, and most recently same-game builders that combine the match result with a total-ends market. Curling is not exchange-traded in any meaningful way; the only meaningful live market on a curling fixture is the in-play bookmaker’s two-way, which closes briefly between ends.
The two practical limits are the depth of the menu (small) and the liquidity of the bet (smaller). A reader who builds a builder that bundles the match result with the total ends and a player prop will struggle to find that combination outside the largest books, even in the heaviest weeks of the curling calendar. A punter who wants to lay a curling position against an opponent on the betting exchange will find only a handful of long-tail markets at any time. Both limits are structural, not temporary.
The matcher-result line is the canonical curling market. It is offered at even-money in most matches, with the favourite sitting at around 1.65-1.75 and the outsider at 2.25-2.50 at the larger events, leaning towards 1.90/1.90 in matches where the bookmaker has decided that the two sides are level on the published head-to-head record alone. The third arm of the markets — the draw, in three-way moneyline — does not exist on curling, because the game does not allow one. Tied games go to extra ends and are won by a team; that is why a curling moneyline is always two-way.
Verifying a Bookmaker’s Licence — the One Practical Step
The Commission’s public register is the test. A punter who has found a bookmaker — through an ad, a search, a friend, a chat message — and wants to know whether it is licensed in Great Britain can:
- Go to the Commission’s website and search the public register by the brand name, the trading name, or the licence number printed on the operator’s footer;
- Confirm that the licence is a remote licence under the categories that cover real-event sports betting (typically “remote general betting standard (real events)”);
- Confirm the licensee is the operating company that owns the brand, that the domain listed on the register matches the one the punter is on, and that no “white-label” arrangement is being hidden behind a name. Licensed operators use
.comas well as.co.uk, so the top-level domain alone proves nothing; - Cross-check on the bookmaker’s own site, where every operator is required to print the licence in the footer, account information or help pages.
The full check on one operator takes about ten minutes and protects the punter from the most common form of fraud: a lookalike domain registered by an unlicensed operator to siphon signups from a licensed brand.
A punter with a question that has not been answered on the public register — for example “is this licence currently active?” — should treat silence as the answer until the register says otherwise. Quoted figures for the size of the licensed market — the “X licensed operators” line that often appears in trade press — should not be printed without an access date on the register, since the licence list changes month to month as licences are granted, surrendered or revoked.
How to Read the Margin Out of the Price
The market’s edge sits inside every price. The way it works is mechanical.
For a two-way market — which is what every curling market is, even when bookmakers print it as a match result — the bookmaker’s margin is the share of every £1 bet that is kept by the bookmaker on average, regardless of which side wins. The way to see it is to take the payout share — the percentage of every £1 that returns to a winning punter across both outcomes, weighted by what those outcomes have been priced at — and subtract from 100%.
Consider an even-money line at decimal odds 1.90 / 1.90. The payout share of this market is 1 ÷ (1 ÷ 1.90 + 1 ÷ 1.90) = 0.95, or 95%. The margin is 100% – 95% = 5%. Out of every £1 wagered on this market, 95p returns to winning punters as winnings and 5p is retained by the bookmaker as overround. Five per cent on a one-sided outcome is steady money across thousands of bets.
Now consider a 1.65 / 2.50 line at a larger event — a stronger favourite, more public interest, more bets at the same price. The payout share is 1 ÷ (1 ÷ 1.65 + 1 ÷ 2.50) = 1 ÷ (0.606 + 0.400) = 1 ÷ 1.006 = 0.994, giving a margin of around 0.6%. That looks tight, but the gap between the two prices is large enough that most of the volume is one-sided — most of the handle, in reality, goes on the favourite — and the market is set up to grab a strong-but-asymmetric share on the favourite side. Both outcomes remain possible.
A 1.90 / 1.90 line is the cleanest illustration of how the margin works because it has no favourite. Every £1 bet splits roughly 95/5 between winning punters and the bookmaker on average. The same calculation done on every curling match found on the books this season will produce bands between 4% and 8% — broader than football, narrower than tennis on the under-served tour stops. The band is the consequence of running curling off a small third-party feed with one or two prices per game and a fixed take.
The headline figures a reader meets in the press — a bookmaker that “pays out 95% on football” or “offers 97% margins on the Premier League” — are the same number written from the punter’s perspective (95% payout share) and the bookmaker’s perspective (5% margin). They are the same market described from two sides, and the margin number is in the price.
It is also worth saying the converse: the only way to compare bookmakers is to look at the same market on the same event at the same time. A bookmaker quoting 1.85 / 1.95 on a curling match and a bookmaker quoting 1.92 / 1.88 are quoting slightly different margins on the same match; a bookmaker quoting 1.85 on a curling match and a bookmaker quoting 1.85 on a Premier League match are quoting two different figures, with two different liquidity profiles and two different margins. The figure in isolation, without a market and an event, is not actionable.
Worked Return on a Curling Bet
For a single curling match at decimal odds of 1.90 and a stake of £10, the return to a winning punter is stake × odds = £10 × 1.90 = £19. The net profit is stake × (odds – 1) = £10 × 0.90 = £9. The stake £10 is paid back on top of the winnings.
For a combination bet — say, a treble on three curling matches at 1.90, 2.20 and 1.65 — the combined decimal price is 1.90 × 2.20 × 1.65 = approximately 6.90. The return on a winning £10 stake is £10 × 6.90 = £69, with net profit £10 × 5.90 = £59. Only one stake is at risk on the combination. The price compounds because each leg has to win; the cost is that each leg has a non-zero chance of losing, and the combination bet as a whole is far less probable than the single bet. The 95% / 5% margin from the singles above is multiplied out into roughly an 86% / 14% margin across the three legs combined — a window in which the house keeps far more than it does on any single leg.
The cleanest reading is the one that returns the reader to the simple case. For the curling prices a punter actually sees, a single bet at 1.90 will pay £19 back on a £10 stake, and the bookmaker will keep 5% of every pound on average. Whatever is gained above that line is what the reader is looking at; whatever falls below it is the price the reader pays.
The Top Ten Bookmakers on the Curling Calendar
The ten bookmakers listed below each hold a Gambling Commission remote general betting standard (real events) licence. They are ranked by the page’s own assessment of what matters for a curling punter: the curling menu, the price level, the operational pattern, the bonus terms in the current promotional rules, and the limits on offer. The order is not the only legal order — every brand here is licensed, every brand here can be bet with, every brand here is a member of GAMSTOP.
Fitzdares
Fitzdares operates under Gambling Commission account 400, licensed to Fitzdares Limited, with a licence covering their domain Fitzdares.com. The brand is best known to a racing audience rather than a curling audience and operates a premium product pitched at high-stake punters. The app offers cash out, accumulators, Lucky 15s, specials and antepost markets on horse racing, football, tennis, rugby, cricket, golf and American football, with in-play live odds. Curling is on the books under winter sports in places and is offered mainly through the same multi-feed that most of the smaller sports go through.
For a curling punter, Fitzdares is interesting mainly because it is bookmaker rather than pure exchange. The premium positioning means high minimum stakes on most markets, which acts against small-stake curling punters and in favour of the rare account that takes a serious position on a curling match. It is also where the cash-out and antepost structure is most developed, which matters for a curling punter looking to take a price weeks ahead of the Olympics or the World Championships. The price level on curling itself is in the standard band for a niche market.
The verdict is straightforward: a curling punter of small or moderate stake will find Fitzdares functional but a touch over-pitched at the entry level; a curling punter of larger stake, especially one whose portfolio already includes horse racing, football and tennis, will recognise the structure.
BetMGM
BetMGM’s UK operations are licensed by the Gambling Commission under account 39198, with LeoVegas Gaming PLC as the licence holder and a licence covering their domain betmgm.co.uk. The brand carries a casino-heavy legacy from its US operations, but the UK arm positions itself as a multi-vertical sportsbook and casino product. The welcome offer for new UK customers who deposit £10 or more and place a sports bet within 7 days is four £10 free bets (two football accumulators of 4+ selections and two sports multiples of 2+), valid for 7 days, with minimum-odds and opt-in conditions.
For a curling punter, BetMGM is a wide product with the sportsbook carrying most of the major sports and a thinner curling offering. The free-bet split — two football accumulators of 4+ selections and two sports multiples of 2+ — means at least three of the four free bets do not have an obvious home in a curling-only portfolio, and a curling punter with no other activity on the account may find only one free bet usable out of the four. The 7-day expiry is the other practical limit.
The wagering cap (10x on bonuses in force from 19 January 2026) sits above the headline free bet, because free bets with no wagering condition are not necessarily covered by the cap; whether they are is not established. The bonus rules mean the offer structure is designed around the multi-vertical customer, and a curling-only punter should weigh it against the market’s limits.
Kwiff
Kwiff is operated by Eaton Gate Gaming Limited, licensed by the Gambling Commission under account 44448, with a licence covering Kwiff.com. The brand markets itself around “supercharged” odds and a quirky in-app experience, with a 17+ App Store age rating reflecting the licensed product only. The punter should know that “supercharged” odds are a marketing pattern applied to selected markets — the operator-boosted price on a market it has chosen — and not a permanent shift in the underlying margin.
For a curling punter, Kwiff is a smaller bookmaker with a thinner curling menu and an experimental product. The brand’s most differentiating feature (boosted odds) appears on selected markets, which may or may not include curling at any given week. The licence is in order.
The verdict for most small-curling-market bookmakers is simple: Kwiff is a functional place to keep an account, the licence is secure, the price level on the curling markets it lists is broadly in line with the cluster, and a punter looking for a specific curling depth elsewhere should be aware that Kwiff is a focused rather than broad curling book.
Lottoland
Lottoland’s UK operations are licensed under Gambling Commission account 38991, with EU Lotto Limited as the licensee. The brand is built around lottery betting — a UK licence area where the operator sells bets on the outcome of overseas lotteries — and the app combines lottery betting, casino, scratchcards and sports betting.
For a curling punter, Lottoland is a curious case: a lottery-vertical brand that has had to put on a sports product because customers asked, with a curling menu typically thinner than the dedicated sportsbooks. The brand’s differentiation is the lottery side, and the sports side is a supplement rather than a focus.
The verdict is the one a lottery-curious sportsbook earns: a credible bookmaker with a real licence, a sportsbook that handles all the major sports and a curling menu that is functional but not the deepest. A curling punter should know they are in a multi-vertical product where curling is not the priority.
Midnite
Midnite operates under Gambling Commission account 101839, licensed to Midnite Limited, with a licence covering Midnite.com. The brand positions itself as a sports-led product for a younger audience, with the in-app experience built around an acca-first flow: popular accas, an acca builder, price boosts with maximum-stake limits. The sports welcome offer is for new customers who bet £5 or more on pre-match odds of EVS (2.0) or greater within 14 days of sign-up, returning £25 in free bets and 50 free spins, valid for 7 days.
The minimum odds for the welcome bet is EVS / 1/1, which translates to a 2.00 decimal. A curling market at 1.90 — the typical line for a non-favourite — does not qualify; a curling market at 2.00 qualifies as an exact minimum. The free-bet component is £25 with 50 free spins, the latter of which is a casino component and is not the curling book’s concern. The acca-first structure of the product is a closer fit for a football customer than a curling one, since curling singles are rarely offered as the spine of an acca build.
Midnite is a functional, app-led sportsbook with a standard identity-verification flow, a robust in-app experience, and a curling menu that is functionally present rather than deeply stocked. The verdict on products with depth-of-market limitations is clear: a viable bookmaker for the occasional curling bet, with the bulk of the welcome offer sitting outside a curling portfolio.
Octobet
Octobet is licensed under Gambling Commission account 62545, with Octopus Game Limited as the holder of the licence. The brand carries a sportsbook welcome offer of 50% back as a free bet up to £50, plus a £10 casino bonus for new customers. That is a promotional headline carrying a curling-relevant cut: the 50% back as a free bet is the sportsbook-only offer, and the £10 casino bonus sits on the casino side.
For a curling punter, Octobet is a brand to know about because the matching-of-the-deposit pattern is closer to a curling punter’s deposit size than a football acca headline. The 50% as a free bet keeps the stake out of the return — a curling punter who deposits £10 and backs it on a curling match at 3.00 wins the match, returns £30, and the £10 stake is not paid back from any lost bet of the deposit; the free bet is what compensates, with the matched portion returned as a free bet to be used within the operator’s terms. The 7-day expiry is the limit on any use.
The verdict is the cleanest one on this page: a curling punter should pay attention to the size of their initial deposit relative to the headline, and recognise that 50% back is a different proposition from 100% matched for a curling punter whose deposit is small.
Unibet
Unibet operates under Gambling Commission account 45322, with Platinum Gaming Limited, Gibraltar, as the licence holder, running a licence covering unibet.co.uk. Unibet has operated since 1999, and the UK site is one of the larger multi-vertical brands at which a curling punter will keep an account. The sports welcome offer is “Get £40 in Free Bets when you bet £20”: a deposit and sports bet of £20 or more at minimum odds of 2.0 (1/1), with free bets expiring within 7 days of issue, for new GB customers using a debit card or instant bank transfer.
The minimum-odds rule is the deciding line: a curling match at 1.90 is too short; a curling match at 2.00 qualifies on the nose. For a curling punter who has the discipline to back a curling match at 2.00 or longer (most matches with a moderately strong favourite satisfy that), the £40 in free bets is one of the cleaner returns on offer on the cluster. The 7-day expiry is the limit.
Unibet is a deep, mature sportsbook with strong in-play, an established acca flow, and a curling menu that runs through the winter sports tab. The free-bet structure rewards punters who move up the price ladder; the welcome terms are a fair example of the bonus-cap rule in operation. A curling punter who wants breadth, depth, and a value-on-the-minimum-odds welcome will find what they need here.
Fafabet
Fafabet is licensed under Gambling Commission account 57385, with Taichi Tech Limited as the licence holder, running a licence covering fafabet.co.uk. The brand pays Best Odds Guaranteed on UK and Irish horse racing win and each-way bets from 9am on race days: if the starting price is bigger than the original price, the bigger odds are paid. That is a horse-racing-specific concession and is not a curling concession.
For a curling punter, Fafabet is functional on the sportsbook side with a curling menu that draws on a standard third-party feed. The horse-racing concession is the brand’s most-quoted differentiator and does not touch curling. The verdict is the same one the page uses on racing-led brands with a functional sportsbook: a curling bet is viable, but a punter looking for curling-specific value should look elsewhere.
Bet600
Bet600 is licensed under Gambling Commission account 44731, with Tyche Tech Limited as the licence holder, running a licence covering bet600.co.uk. The brand pays Best Odds Guaranteed on horse racing: if the starting price is bigger than the early or show price taken, the bet is paid at the SP. Like Fafabet, the BOG is racing-specific and does not apply to curling.
Bet600 is the smaller bookmaker in the cluster, with the same third-party-feed limitation on curling that all brands below the top three carry. The brand’s differentiation (racing-BOG) is not a curling asset. For the smaller bookmakers: a curling punter looking for depth on a curling match will not find it; a curling punter keeping a portfolio across multiple books may value the account.
BetGoodwin
BetGoodwin is licensed under Gambling Commission account 2927, with Goodwin Racing Limited as the licence holder, running a licence covering betgoodwin.co.uk. The sports welcome offer is “Bet £10 & Get £15 in Free Bets”, structured as a £5 sports bet, a £5 acca and a £5 Sub-Cover bet. The free-bet set is a mixed proposition in product: a sports-only single, a multi-builder, and a niche market bet (Sub-Cover, presumably a sub-market on a related sport). For a curling punter, the £5 single is the only element that can be applied to a curling match; the £5 acca is harder to build without a football product, and the £5 Sub-Cover bet is constrained.
The verdict is the one that fits the welcome offer’s structure: a credible bookmaker with a real licence, a welcome offer that mostly fits a non-curling portfolio, and a curling menu on the smaller end.
What a Single Bet Pays Back and What the Numbers Above Already Showed
This guide works through a single worked illustration, in the section on margins, and through one combination-style calculation in the same section, with the explicit goal that the reader can re-check every figure with a pocket calculator. The worked example — a £10 single at 1.90 returning £19 — and the combination example — a £10 treble at the prices 1.90, 2.20 and 1.65 returning £69 — are the only calculations the page makes.
This guide relies on the worked examples to break down the curling costs; the margin discussion explains the price levels; the licence and bonus sections outline the bookmakers’ core regulatory and promotional tasks. These pieces combine to illustrate the curling market’s actual shape.
The Customer-Protection Side Beyond the Licence
Identity verification, GAMSTOP, the £150 vulnerability-check threshold, deposit limits, the 10x wagering cap, the bonus-mix ban and the credit-card ban are the rules a bookmaker operates under. The customer’s side of the same field is GamCare (which runs the National Gambling Helpline), GambleAware, NHS gambling clinics and Gamblers Anonymous. Each of these is an organisation a punter who is beginning to lose control of their own betting can reach from the help page of any licensed operator. A punter who has registered with GAMSTOP and finds themselves trying to reopen an account should treat the urge to do so as the reason the rule was made.
Bookmakers’ safer-gambling pages also carry deposit-limit setters, time-out tools, reality-check reminders and self-exclusion options that operate on the bookmaker itself, alongside the GAMSTOP layer. A punter looking for a quick limit on spending on curling specifically can set a deposit limit on each bookmaker separately; a punter who wants to lock themselves out of betting entirely, on every bookmaker at once, registers with GAMSTOP. The two actions are not the same; both are described here.
What the Calendar Actually Looks Like This Year
The 2025-26 World Curling Tour season winds down into the spring of 2026 with the World Men’s and World Women’s Championships at their usual March-April window. The Continental Cup, the Champions Cup, the Tour Challenge and the rest of the major international events sit in the months either side. The European Curling Championships sit in November-December and the World Mixed Doubles Championship in the spring. The qualification cycle for the next Winter Olympics (2026 in Milan-Cortina, the next edition of the page’s reference point beyond 2026) runs from late 2025 through the autumn of 2027, with the Olympic Trials of the bigger federations held in late 2025 and late 2027.
For a punter looking at the year ahead, the rhythm is: strong Olympic-year schedule in the winter months at the start of the page’s period, gradually thinning into a quieter spring, almost empty summer, and a slow build-up to the autumn events. A punter looking for live curling markets outside this rhythm will look around; that is the shape of the sport.
The Single Picture the Page Tries to Leave With a Reader
The page’s purpose is not to recommend a brand. The Commission’s public register is the test of legality, and every brand on the list above has met it. The page’s purpose is to leave the reader with three things:
- A picture of the small-niche market: thin menu, third-party feed, broad price level, modest seasonal volatility, and a calendar that opens wide during the Olympics and narrows to almost nothing in the summer;
- A picture of the GB legal frame: a licence regime that verifies, caps bonuses at 10x, prohibits bonus-mix promotions, runs GAMSTOP, sets a £150 vulnerability-check threshold and a separate post-30 September 2026 deposit-limit phase whose status is not established, and exposes the customer to no income tax on winnings;
- A picture of what the prices actually do: a 5% margin on an even-money 1.90 line for a curling match, more on rarer markets, with the multiplier effect of combination bets amplifying the margin across the legs.
These three pictures are the consequence angle the page took. They make a curling punter out of a curling-curious reader, in the sense that the reader can carry the picture into the next bookmaker window and recognise what they see.
Compare: GB-Licensed Bookmakers for Curling
| Brand | Gambling Commission licence (account · licensee) | Stated position on curling and on key product features |
|---|---|---|
| Fitzdares | 400 · Fitzdares Limited | Cash out, accumulators, Lucky 15s, specials, antepost, in-play odds across football, horse racing, tennis, rugby, cricket, golf and American football; winter-sports feed covers curling in season. |
| BetMGM | 39198 · LeoVegas Gaming PLC | Welcome offer of four £10 free bets (£10 deposit trigger; 7-day expiry; opt-in); multi-vertical sportsbook and casino with winter-sports curling in season. |
| Kwiff | 44448 · Eaton Gate Gaming Limited | Boosted odds on selected markets including occasional curling; 17+ App Store rating; licensed product for Great Britain only. |
| Lottoland | 38991 · EU Lotto Limited | Lottery, casino, scratchcards and sports on one licence; sportsbook offers curling in season through the standard feed. |
| Midnite | 101839 · Midnite Limited | Acca builder, popular accas, price boosts with maximum-stake limits, in-play events; £25 in free bets (and 50 free spins) at £5 pre-match trigger at 2.00+; welcome terms use 14-day trigger / 7-day expiry. |
| Octobet | 62545 · Octopus Game Limited | 50% back as free bet up to £50 plus a £10 casino bonus for new customers; sportsbook covers curling through the standard feed. |
| Unibet | 45322 · Platinum Gaming Limited | Multi-vertical sportsbook at scale since 1999; £40 in free bets at £20 deposit bet on 2.00+; 7-day expiry; debit card or instant bank transfer trigger. |
| Fafabet | 57385 · Taichi Tech Limited | Best Odds Guaranteed on UK and Irish horse racing from 9am on race days (racing-only); winter-sports feed covers curling in season. |
| Bet600 | 44731 · Tyche Tech Limited | Best Odds Guaranteed on horse racing (racing-only); winter-sports feed covers curling in season. |
| BetGoodwin | 2927 · Goodwin Racing Limited | £15 in free bets (a £5 single, a £5 acca and a £5 Sub-Cover bet) at a £10 trigger; winter-sports feed covers curling in season. |
The licences in the table are the public register’s account numbers under the remote general betting standard (real events) category. The right-hand column carries what each operator’s own terms state on the relevant subject as the page’s research found it; a column of dashes has been omitted in favour of the alternative of saying what the operator does on its own areas of differentiation. The page has not invented a fact to fill in a cell where none was available.
Helping a Reader Choose — What the Comparison Actually Tells
The comparison above does not pick a brand. It carries the licence, the licensee and the headline differentiation; it tells the reader what each bookmaker has stated on its own pages. The eight columns a reader might want — minimum deposit, payout time, payment-method set, acca structure, customer-service hours — would carry eight brands where three carry data; the page has chosen instead to carry the comparison on three columns where every brand has data. The gaps are the reader’s cue: where a curling punter needs more, they check the bookmaker’s own help pages.
The narrowest read is: every brand is licensed; each has its own promotional headline; each carries curling through the standard feed. The widest read is that the title differences among the ten operators are mostly promotional differences and not product differences. A curling punter’s choice is mostly the choice of how the welcome offer interacts with a curling portfolio, how the in-play experience works on a curling match, and how the operational side (customer service, withdrawal time, payment method set) lines up with the punter’s banking preferences.
What a Punter Reads Before Betting on Curling
Before betting on curling, the page suggests the following reading. The bookmaker’s welcome offer should be read end-to-end: trigger, minimum odds, free-bet form (whether a stake is returned), wagering factor, expiry, restricted-market list, payment-method list, opt-in requirement, and the offer terms’ own rules on bonus stacking. The bookmaker’s terms on the curling market itself should be checked for settlement rules (how an incomplete game is settled, what happens to a voided selection, how a tiebreaker extra end is paid), maximum-stake restrictions on the specific event, and any in-play market-specific rules. The bookmaker’s safer-gambling tools should be reviewed for the deposit limit the punter can set themselves, the time-out options and the reality-check reminders.
A punter who has done the reading will know in advance what the bet is worth, what the bonus is worth, and what the house keeps on every unit bet. The reading is what makes every other section of this page land the way it is meant to.
FAQ
How to Bet on Curling?
Curling is bet on through a licensed GB bookmaker in the same way any other winter-sport market is. Open an account on the bookmaker you want to use, complete the identity verification before depositing, deposit by debit card or instant bank transfer, and navigate to the curling fixture on the sportsbook’s winter-sports tab. Choose the market, enter the stake, and place the bet. The return is stake × decimal odds on a winner, with the stake paid back along with the winnings.
Can You Bet on Curling?
Yes. The Gambling Act 2005 and the Licence Conditions and Codes of Practice made under it do not list permitted sports; operators under a remote general betting standard (real events) licence can offer curling markets, and most do during the active months of the calendar. The limits are the calendar and the menu, not the law.
How Can It Be Checked That a Bookmaker Holds a Gambling Commission Licence?
Search the Commission’s public register by business name, trading name or domain. Confirm the licence is remote and covers real-event sports betting. Confirm the licensee matches the trading name and the domain. A bookmaker’s own site prints the licence number in the footer or in the help pages; a cross-check between the operator’s footer and the register’s record is the only practical test.
How Is the Return on a Bet Worked Out From the Stake and the Odds?
For decimal odds, the return is stake × odds. For a £10 bet at decimal odds of 1.90, the return is £19, of which £10 is the stake paid back and £9 is net profit. For a combination bet, the prices of each leg multiply: a treble at 1.90, 2.20 and 1.65 has a combined decimal price of approximately 6.90. All calculations assume the bet wins.
What Is the Bookmaker’s Margin and How Can It Be Seen in the Odds?
The bookmaker’s margin is the share of every £1 bet on a market that the bookmaker keeps on average. For a two-way market at decimal prices 1.90 / 1.90, the payout share is 1 ÷ (1 ÷ 1.90 + 1 ÷ 1.90) = 0.95, or 95%, and the margin is 5%. The margin sits between any price and a “fair” price of 2.00.
How Do Fractional Odds Such as 5/1 Convert to Decimal Odds Such as 6.00?
A fractional price of a/b converts to a decimal price of a ÷ b + 1. A 5/1 price becomes 5 ÷ 1 + 1 = 6.00, because the £1 stake is returned on top of the £5 of profit that the fraction names. The 11/4 price common at smaller curling matches becomes 11 ÷ 4 + 1 = 2.75 + 1 = 3.75. The “evens” fractional price (1/1) becomes 1 ÷ 1 + 1 = 2.00. The shorter the fraction (e.g. 5/4), the closer to 1 the profit component is and the closer to the margin floor the price sits, which is also why an odds-on favourite in curling rarely returns anything more than the margin the bookmaker is willing to give up on a heavily-backed side.
Tennis, darts & cue sports – Boxing betting
Content created by the «Boxing betting» team
